



- Technology
- Generative AI Market
Generative AI Market Size, Share, and Growth Forecast 2026 - 2033
Generative AI Market by Offering (Infrastructure, Software, Services), Data Modality (Text, Image, Video, Audio & Speech, Code, Multimodal, Other), Application (Content Generation & Management, Knowledge Management & Discovery, Code Generation & Software Engineering, Generative Analytics, Autonomous Task Execution, Other), and Regional Analysis, 2026 - 2033

Generative AI Market Size and Trends Analysis
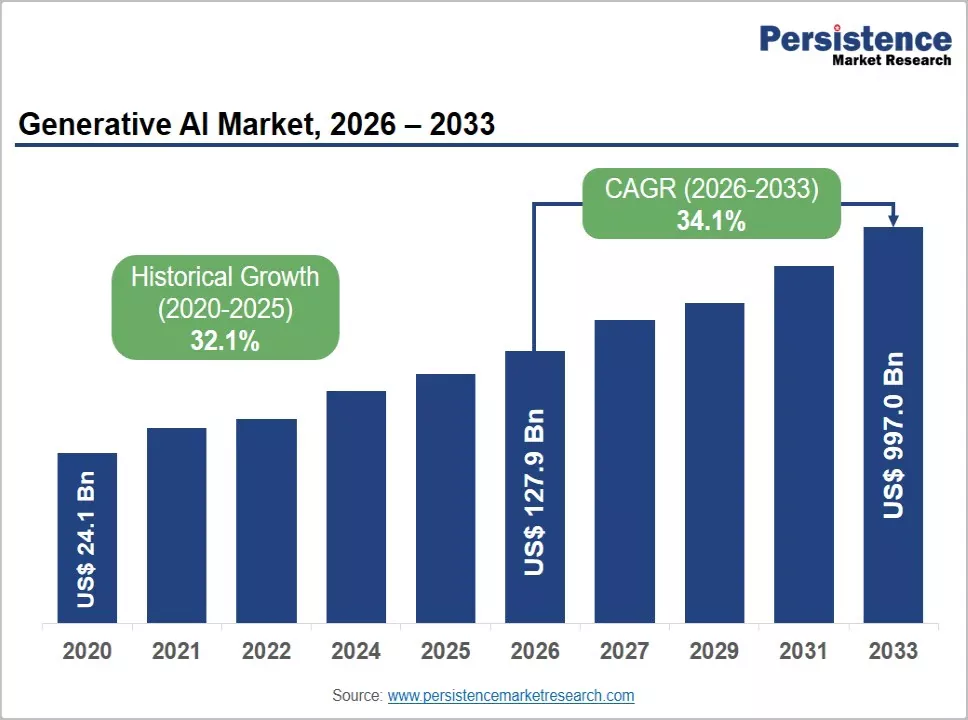
The global generative AI market size is expected to be valued at US$127.80 billion in 2026 and is projected to reach US$997.0 billion by 2033, growing at a CAGR of 34.1% between 2026 and 2033, driven by the rapid integration of generative AI into enterprise operations, where large language models (LLMs), diffusion-based image synthesis, multimodal foundation models, and retrieval-augmented generation (RAG) architectures are transforming content creation, software development, and knowledge-work automation.
The market's expansion reflects rising enterprise investment and growing adoption across industries. The United States Executive Order on Safe, Secure, and Trustworthy Artificial Intelligence, issued in October 2023, established a federal policy framework for AI safety and governance. Meanwhile, Microsoft's cumulative investment of US$13 billion in OpenAI has supported the integration of generative AI capabilities into enterprise productivity tools, making these technologies accessible to a broad global user base.
Key Industry Highlights:
- Regional Leader: North America's US$60.07 billion generative AI market in 2026 reflects a structural first-mover advantage built on co-located model developers, hyperscaler infrastructure, and enterprise buyers, a combination that reinforces itself as application ecosystems deepen around leading foundation models through 2033.
- Fastest-Growing Region: Asia Pacific is likely to be the fastest-growing regional market, expanding at an estimated CAGR of 36%, outpacing every other geography. Government-mandated AI development strategies such as China's "New Generation Artificial Intelligence Development Plan" and India's IndiaAI Mission are channeling sovereign capital into model research, GPU procurement, and AI startup ecosystems.
- Leading Segment: Infrastructure's 46.0% revenue dominance reflects a fundamental economic reality: every text token generated, image synthesized, or autonomous agent deployed consumes GPU compute, and NVIDIA's accelerator supply position means infrastructure spending will remain the largest cost category for buyers and the largest revenue category for the market through the forecast period.
- Fastest-Growing Segment: Video generation is emerging as the highest-velocity modality expansion, with OpenAI's Sora and Google DeepMind's Veo platforms commercializing text-to-video synthesis for media, advertising, and enterprise communications use cases, a market that barely existed at commercial scale before 2024 and is now attracting dedicated enterprise budget allocation.
- Key Market Opportunity: The agentic AI opportunity, autonomous, multi-step task execution across enterprise systems, represents the most strategically consequential near-term expansion vector, with Salesforce's Agentforce and Anthropic's Model Context Protocol creating the standardized interfaces that enable production-scale agent deployment and justify premium software pricing for orchestration-layer vendors.
Market Dynamics
Drivers - Hyperscaler Infrastructure Commitment and GPU Compute Expansion
The capital expenditure ambitions of cloud hyperscalers are the single most decisive supply-side force shaping generative AI market growth. Microsoft, Amazon Web Services (AWS), and Google LLC collectively announced over US$200 billion in combined data center and AI infrastructure investment commitments for 2025, per their respective earnings disclosures. These investments underwrite the GPU clusters and tensor processing units (TPUs) that make foundation model training and inference commercially viable.
Enterprise buyers benefit directly as hyperscalers amortize infrastructure costs across millions of API calls; the per-token cost of generative AI inference has fallen sharply, expanding the addressable buyer pool beyond hyperscale technology firms to mid-market enterprises in financial services, healthcare, and manufacturing. This cost deflation dynamic accelerates adoption far faster than conventional enterprise software cycles.
Rapid Enterprise Adoption Driven by Measurable Productivity Returns
Documented productivity gains are converting executive skepticism into sustained budget allocation. A 2024 study published by the National Bureau of Economic Research (NBER) found that customer service agents using generative AI assistance resolved 14% more issues per hour than unassisted peers.
Similarly, GitHub Copilot, Microsoft's AI-powered code-completion tool, reported that developers using it completed coding tasks 55% faster, according to GitHub's internal research. These quantified returns are directly influencing enterprise procurement decisions, particularly in software engineering, legal contract review, and financial report generation. Chief information officers are no longer evaluating generative AI as experimental technology. They are integrating it into operational workflows with defined ROI thresholds and vendor SLAs.
Restraints - Regulatory Fragmentation and Compliance Uncertainty
The European Union's Artificial Intelligence Act, which entered into force in August 2024, imposes tiered compliance obligations on general-purpose AI models with systemic risk designations, including mandatory transparency disclosures, adversarial testing requirements, and incident reporting to the European AI Office. At the same time, divergent national frameworks in the U.S., China, and the United Kingdom create a compliance patchwork that increases the cost and complexity of cross-border generative AI deployment.
Enterprises operating in regulated sectors such as financial services and pharmaceuticals must navigate sector-specific AI guidance from bodies including the U.S. Securities and Exchange Commission (SEC) and the European Medicines Agency (EMA), compounding the compliance burden and extending procurement timelines.
Hallucination Risk and Output Reliability Constraints
Foundation models remain susceptible to generating factually incorrect, contextually incoherent, or legally problematic outputs, a phenomenon known as hallucination. This reliability gap is a structural restraint in high-stakes deployment contexts including clinical decision support, legal document drafting, and financial advice. Despite advances in reinforcement learning from human feedback (RLHF) and grounding techniques such as RAG, enterprises in liability-sensitive verticals are maintaining human-in-the-loop review requirements that limit full automation and increase operational costs, partially offsetting the productivity gains that justify adoption.
Opportunities - Vertical-Specific Foundation Models and Domain-Adapted LLMs
The generative AI landscape is shifting from general-purpose models toward domain-adapted foundation models fine-tuned on proprietary datasets. Healthcare and life sciences present the most immediate opportunity. Google DeepMind's Gemini-based medical reasoning models and Microsoft's investment in Nuance Communications for clinical documentation automation illustrate how vertical specialization commands premium pricing and stronger customer retention. Enterprises that develop or license models trained on sector-specific corpora, clinical trial data, financial regulatory filings, and engineering schematics will capture disproportionate margin relative to horizontal model providers. The window for differentiation is narrowing as foundation model costs fall, making now the critical moment to establish vertical positioning.
Agentic AI Workflows and Enterprise Automation Platforms
Autonomous AI agents capable of executing multi-step tasks across enterprise systems represent the next material demand frontier. Salesforce's Agentforce platform, launched in late 2024, and Microsoft's Copilot Studio both enable organizations to deploy LLM-orchestrated agents that interact with CRM systems, databases, and external APIs without continuous human prompting. This shifts generative AI from a content generation tool to an operational automation layer, expanding total addressable market substantially. Software vendors, systems integrators, and managed service providers that build orchestration capabilities on top of foundation model APIs are best positioned to capture this opportunity as enterprises move from pilot programs to production-scale agentic deployments.
Category-wise Insights
Why Does Infrastructure Dominate the Generative AI Market Revenue Mix?
The infrastructure segment is expected to account for 46.0% of the global generative AI market in 2026, reaching US$58.79 billion. Its dominance is driven by the growing need for specialized computing, networking, and storage capabilities to support model training, inference, and embedding generation. Hyperscalers and enterprises are expanding their procurement of NVIDIA H100 and H200 GPU clusters, while specialized AI cloud providers such as CoreWeave offer bare-metal GPU infrastructure tailored to large language model (LLM) workloads. Financial institutions developing proprietary risk models and healthcare networks deploying on-premises inference systems to maintain data sovereignty are among the key buyers supporting the segment's leading position.
Software is likely to be the fastest-growing offering segment, propelled by the rapid proliferation of API-accessible foundation model platforms and enterprise AI application layers. OpenAI's GPT-4o API and Anthropic's Claude API, both released or updated in 2024, enabled software developers to embed generative AI capabilities without owning model infrastructure, dramatically lowering the barrier to enterprise software integration and accelerating software segment revenue.
Data Modality Analysis
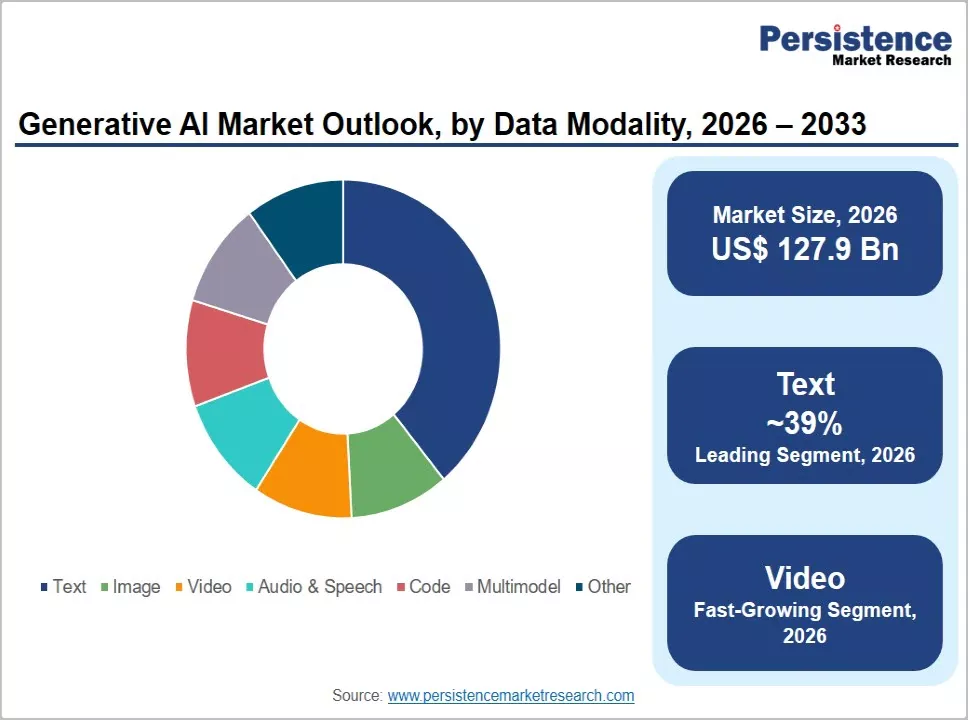
Text is expected to account for 39.0% of the global generative AI market in 2026, equivalent to US$49.84 billion, reflecting its foundational role across virtually every enterprise workflow that generative AI currently addresses. Legal teams at firms including Clifford Chance deploy LLM-powered contract analysis tools that extract obligations, flag anomalies, and summarize lengthy agreements in minutes. Marketing organizations use text generation at scale for personalized email campaigns, product description libraries, and multilingual content localization, use cases where the return on investment is measurable and immediate. The maturity of the text modality, anchored by years of transformer architecture refinement since Google's publication of the original "Attention Is All You Need" paper in 2017, sustains its dominant position.
Video is likely to be the fastest-growing data modality, accelerated by the commercial launch of OpenAI's Sora text-to-video model in 2024 and Google DeepMind's Veo platform. Media production companies and advertising agencies are adopting AI video synthesis to generate short-form content and visual effects assets at a fraction of traditional production costs, opening a previously inaccessible market segment.
What Is Fueling Demand for Content Generation and Management at Scale?
Content generation & management is expected to account for 32.0% of the global generative AI market in 2026, equivalent to US$40.90 billion, driven by the sheer volume of content that modern enterprises must produce across digital, regulatory, and commercial channels. Retail and e-commerce enterprises use generative AI to produce thousands of unique product descriptions, A/B-tested landing page variants, and multilingual customer communications simultaneously, workflows that would require prohibitively large editorial teams to execute manually. Publishing groups and media conglomerates, including Axel Springer, have formalized generative AI content integration into editorial workflows, treating AI-assisted drafting as a production efficiency tool under established editorial governance frameworks.
Autonomous task execution is predicted to be the fastest-growing application segment, catalyzed by the emergence of production-ready agentic AI frameworks. Anthropic's Model Context Protocol (MCP), released in late 2024, established a standardized interface enabling AI agents to interact with external tools and data sources, a development that meaningfully lowered the engineering cost of deploying autonomous agents in enterprise environments and triggered a wave of agentic workflow adoption across IT operations and procurement functions.
Regional Insights
North America Generative AI Market Trends and Insights
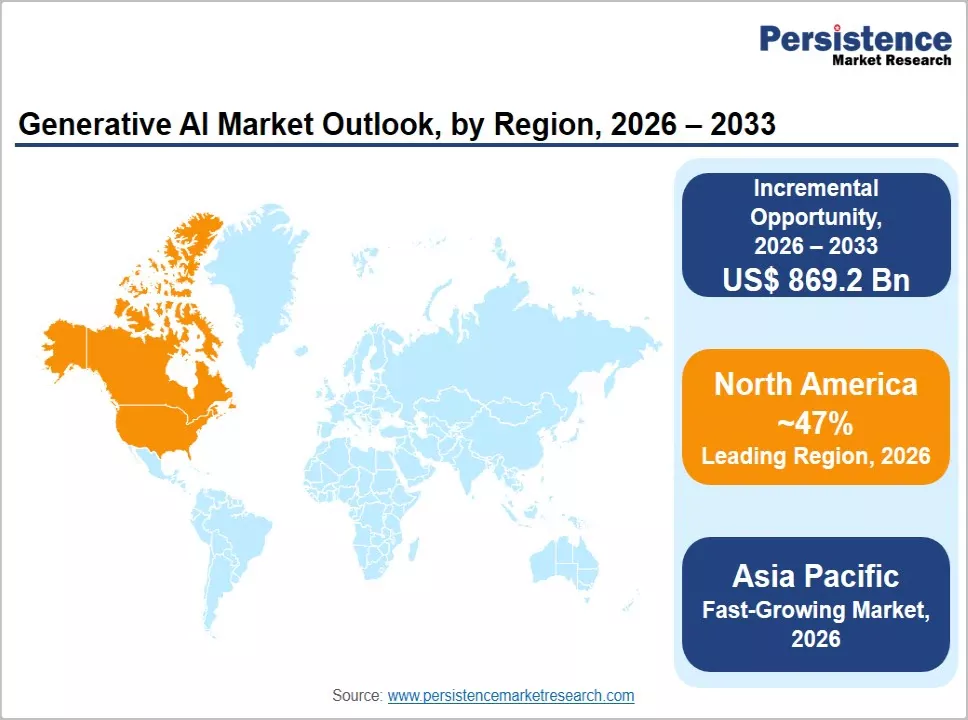
North America is expected to account for 47.0% of the global generative AI market in 2026, representing US$60.07 billion, anchored by the concentration of foundation model developers, hyperscaler infrastructure, and enterprise technology buyers in the U.S. The CHIPS and Science Act (2022) reinforced domestic semiconductor production capacity, securing the GPU supply chains that underpin generative AI model development. North America's lead is structurally durable.
The venture capital deployment into generative AI startups in the region exceeded US$33 billion in 2024, per PitchBook data, sustaining a pipeline of model innovation and application development that competing regions have not yet replicated.
U.S. Generative AI Market
The U.S. is likely to represent an estimated 85% of the North American generative AI market, equivalent to approximately US$51.06 billion in 2026. Federal agency adoption, including the Department of Defense's generative AI pilot programs through the Chief Digital and Artificial Intelligence Office (CDAO), is adding sovereign demand alongside commercial enterprise uptake, a dynamic that will intensify as government procurement frameworks mature through 2027.
Europe Generative AI Market
Europe is likely to account for 19.0% of the global generative AI market in 2026, representing US$24.28 billion, within a regulatory environment that is simultaneously the world's most demanding and most consequential for long-term market architecture. The EU AI Act's general-purpose AI provisions are compelling both domestic and international model providers to invest in EU-compliant model auditing and data governance infrastructure. European enterprises, particularly in financial services and automotive manufacturing, are allocating generative AI budgets cautiously but consistently, with deployment focused on use cases where explainability and auditability are achievable.
Germany Generative AI Market
The Germany generative AI market is predicted to represent 25.0% of the European regional market in 2026, equivalent to US$6.07 billion. Industrial automation demand, specifically LLM-assisted engineering documentation, predictive maintenance reporting, and supply chain optimization at automotive and machinery manufacturers, drives adoption. Siemens AG's integration of generative AI into its Industrial Copilot platform, announced in 2023, exemplifies the deployment model that German engineering enterprises are scaling through 2026 and beyond.
U.K. Generative AI Market
The U.K. generative AI market is expected to represent 23.0% of the Europe regional market in 2026, equivalent to US$5.58 billion. Financial services firms in the City of London, including asset managers and investment banks, deploying LLMs for research synthesis and client reporting, constitute the primary demand vertical. The U.K. Government's pro-innovation regulatory stance, articulated through the AI Opportunities Action Plan published in January 2025, signals further public-sector demand stimulus through targeted investment in sovereign AI compute capacity.
France Generative AI Market
The France generative AI market is likely to represent 15.0% of the European regional market in 2026, equivalent to US$3.64 billion. Mistral AI, the Paris-based foundation model company valued at approximately US$6 billion following its 2024 funding round, has positioned France as Europe's most prominent indigenous model developer, attracting co-investment from the French Government and the European Investment Bank. This domestic foundation model ecosystem is stimulating enterprise adoption among French corporations seeking data-sovereign alternatives to US-headquartered model providers.
Which Region Will Drive the Fastest Generative AI Market Growth Through 2033?
Asia Pacific is anticipated to account for 27.0% of the global generative AI market in 2026, representing US$34.51 billion, and is the fastest-growing regional market, expanding at an estimated CAGR of 36%, outpacing every other geography.
Government-mandated AI development strategies such as China's "New Generation Artificial Intelligence Development Plan" and India's IndiaAI Mission (funded at approximately INR 10,371 Crore by the Ministry of Electronics and Information Technology) are channeling sovereign capital into model research, GPU procurement, and AI startup ecosystems, which are the primary acceleration force. The region's combination of policy urgency, large developer talent pools, and rapidly digitizing enterprise sectors makes it the dominant growth engine for the generative AI industry through 2033.
China Generative AI Market
The China generative AI market is forecast to represent 50.0% of the Asia Pacific regional market in 2026, equivalent to US$17.25 billion. Baidu's ERNIE Bot, Alibaba Cloud's Qwen model series, and Huawei's Pangu foundation model are competing for enterprise and consumer market share in a domestic ecosystem insulated from US-based competitors by regulatory design. Export controls on advanced semiconductors imposed by the U.S. Department of Commerce are accelerating Chinese firms' investment in domestic chip alternatives, a constraint that simultaneously shapes and intensifies local innovation.
Japan Generative AI Market
The Japan generative AI market is set to represent 13.0% of the Asia Pacific regional market in 2026, equivalent to US$4.49 billion. Manufacturing and robotics integration, specifically, using LLMs to generate process documentation, quality control reports, and predictive maintenance insights within Toyota Production System-aligned workflows, represents Japan's primary enterprise demand driver. The Japanese Government's AI Strategy Council has identified generative AI adoption as a core pillar of its productivity agenda, providing regulatory clarity that is accelerating corporate deployment decisions.
India Generative AI Market
The India generative AI market is predicted to represent 12.0% of the Asia Pacific regional market in 2026, equivalent to US$4.14 billion. India's large IT services sector, led by firms including Tata Consultancy Services (TCS), Infosys, and Wipro, is both a deployer and an exporter of generative AI capabilities, embedding LLM-powered services into client delivery models globally. The IndiaAI Mission's compute infrastructure fund is expected to add meaningful domestic GPU capacity by 2027, reducing dependence on hyperscaler cloud access and enabling a broader range of domestic foundation model development.
Competitive Landscape
The global generative AI landscape is structurally tiered rather than conventionally fragmented. A small group of foundation model developers, OpenAI, Anthropic, Google DeepMind, and Meta Platforms, controls the most capable base models and sets the competitive floor for the entire industry. Infrastructure providers, led by NVIDIA Corporation through its GPU monopoly on AI accelerator supply, occupy a structurally advantaged position that neither model developers nor application builders can circumvent.
The application layer is the most contested tier, where Microsoft, Salesforce, Adobe, IBM, and Accenture compete on enterprise integration depth, vertical specialization, and trust credentials rather than raw model capability. In Asia, Alibaba Cloud, Baidu, and regional cloud providers compete within sovereign market boundaries, insulated from but increasingly influencing the global competitive calculus.
Key Industry Developments:
- October 2026: Anthropic launched in-country inference for Claude models in India through Amazon Bedrock, enabling Claude Opus 5, Sonnet 5, and Haiku 4.5 workloads to be processed within India and supporting data-residency requirements for regulated enterprises.
- September 2026: OpenAI halted the public release of its GPT-6.1 Astra model after internal testing found it fell short of safety standards for scope, authorization, and transparency, highlighting tighter safeguards for increasingly autonomous generative AI systems.
- March 2026: NVIDIA launched Dynamo 1.0, an open-source inference platform designed to scale generative and agentic AI workloads, improving Blackwell GPU inference performance by up to seven times.
Companies Covered in Generative AI Market
- OpenAI
- Anthropic
- NVIDIA
- Adobe
- Microsoft
- Google Inc.
- Amazon Web Services
- Meta Platforms
- IBM
- Accenture
- Salesforce
- Alibaba Cloud
- Baidu
- Stability AI
- Synthesia
Frequently Asked Questions
The global generative AI market is likely to be valued at US$127.80 billion in 2026 and is projected to reach US$997.0 billion by 2033, growing at a CAGR of 34.1%. Accelerating enterprise adoption of large language models for content generation, code automation, and knowledge management, supported by sustained hyperscaler infrastructure investment, is the primary growth catalyst.
Sustained capital investment by cloud providers and the measurable productivity gains documented in enterprise deployments are the two principal growth drivers. The European Union AI Act and the U.S. Executive Order on AI are simultaneously creating compliance demand, as enterprises invest in responsible AI governance frameworks to meet mandatory requirements set by these regulatory bodies.
The infrastructure segment is set to hold the largest share at 46.0% of the global generative AI market, because model training and inference workloads require specialized GPU compute that no enterprise or model developer can substitute. This structural dependency on purpose-built AI accelerators, dominated by NVIDIA Corporation's H100 and Blackwell GPU families, is durable and is unlikely to erode materially through the 2033 forecast horizon.
North America is expected to dominate the global generative AI market with a 47.0% share, equivalent to US$60.07 billion in 2026, anchored by the geographic concentration of the world's leading foundation model developers and hyperscale cloud infrastructure. Enterprise technology spending depth and a pro-innovation federal policy environment, including targeted AI investment under the CHIPS and Science Act, reinforce the region's structural lead into the next decade.
Domain-adapted foundation models for regulated industries, particularly healthcare, legal services, and financial compliance, represent the most commercially attractive opportunity, commanding premium pricing over general-purpose model APIs. Systems integrators and vertical software vendors that combine proprietary sector-specific training data with production-ready compliance infrastructure are best positioned, enabled by the falling cost of fine-tuning foundation models on private enterprise datasets.
The generative AI market's leading companies include OpenAI, Anthropic, Google DeepMind, Microsoft, NVIDIA, Meta Platforms, Amazon Web Services, Adobe, Salesforce, IBM, Alibaba Cloud, and Baidu. Competition is intense at the application layer and moderating at the infrastructure tier, where NVIDIA's accelerator supply position creates a durable structural advantage. The primary bases of competition are model capability, enterprise integration depth, vertical specialization, and regulatory compliance readiness.


